
El plan de Medicare de sus padres termina. ¿Qué hacer ahora?
Cerca de 3.8 millones de beneficiarios de Medicare perderán su plan actual para 2027 porque las aseguradoras salen de ciertos condados o no renuevan contratos.
Este episodio en inglés utiliza voces generadas con IA. El guion fue investigado, redactado y verificado por el equipo editorial de families.care con fuentes oficiales de CMS y Seguro Social.
Leer guía escrita complementaria (EN) →
El plan de Medicare de sus padres termina. ¿Qué hacer ahora?
Escuche abajo en inglés con subtítulos o salte directamente a cualquier capítulo.
Saltar a capítulo (toque la marca de tiempo para ir al audio y actualizar enlace #t=):
Puntos clave
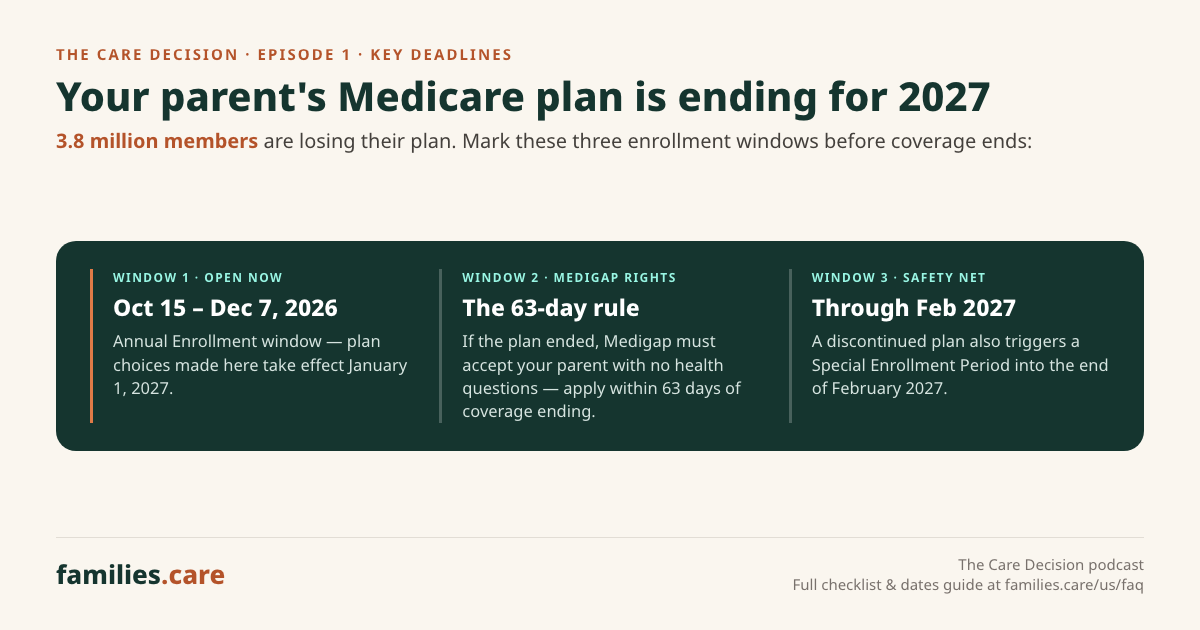
- 01La inscripción anual de Medicare va del 15 de octubre al 7 de diciembre de 2026; los cambios entran en vigor el 1 de enero de 2027.
- 02Si el plan actual no se renueva, existe un Período Especial de Inscripción hasta fines de febrero de 2027.
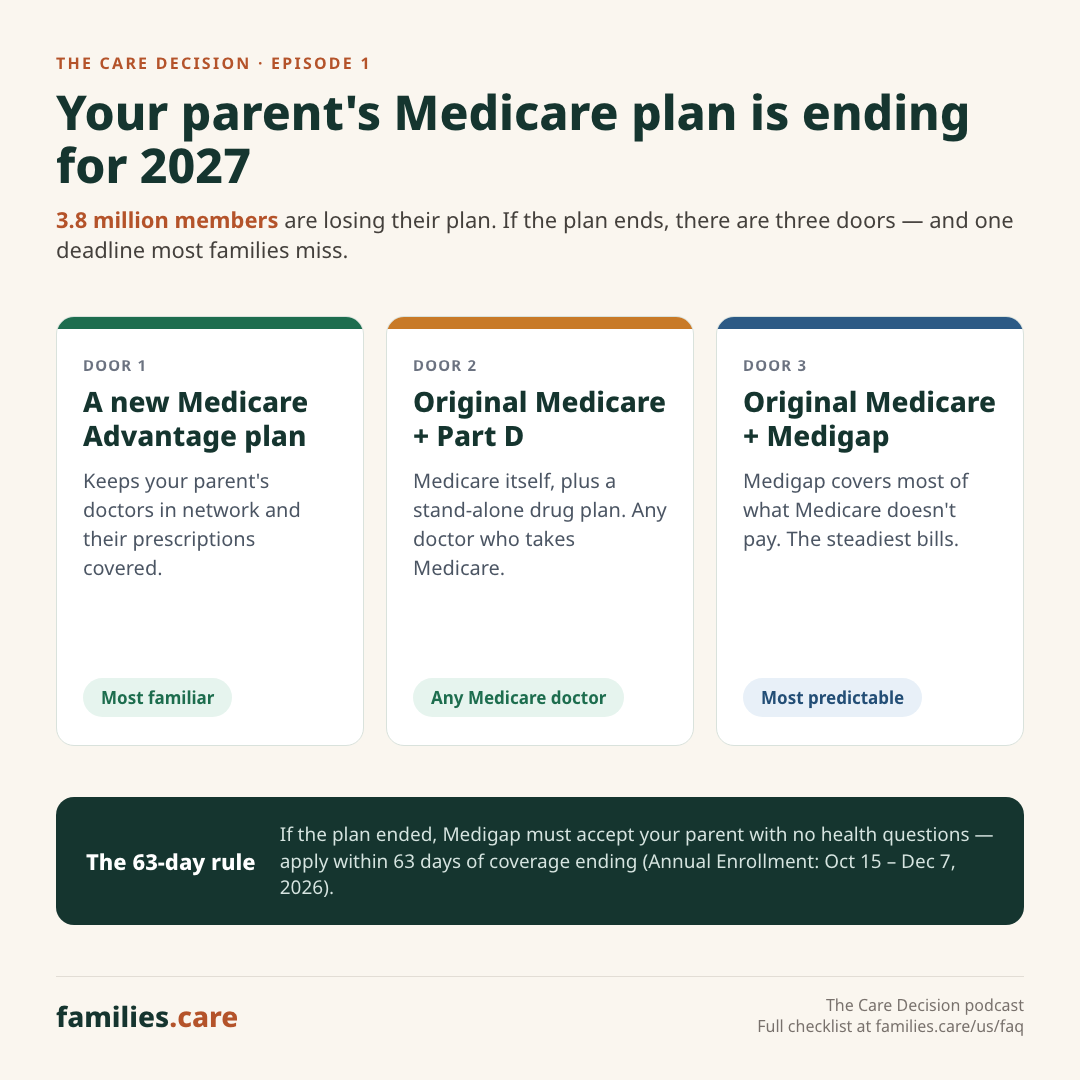
- 03Ventana Medigap de emisión garantizada: solicite dentro de los 63 días posteriores al fin de la cobertura anterior para evitar evaluación médica.
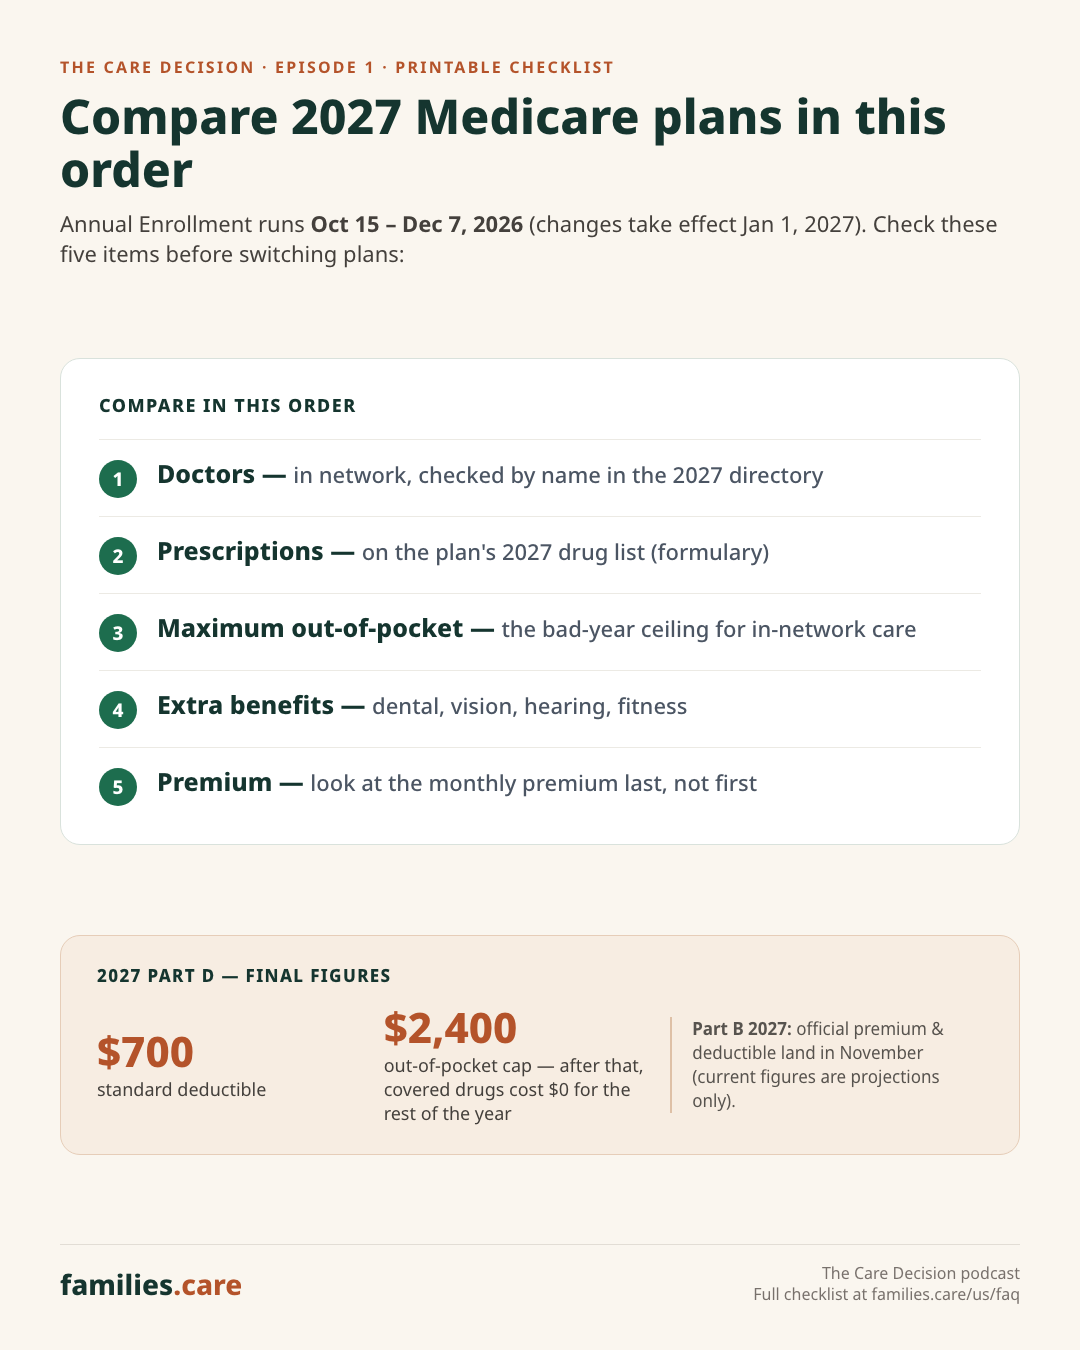
- 04Orden correcto de comparación: médicos en red → medicamentos → gasto máximo anual de bolsillo (MOOP) → beneficios adicionales → prima mensual al final.
- 05Cifras oficiales Parte D 2027: deducible estándar de $700 y tope anual de bolsillo de $2,400.
- 06El ajuste por costo de vida (COLA) del Seguro Social 2027 es de 3.6%.
Lista familiar de verificación cuando termina un plan Medicare
Marque cada paso mientras revisa médicos, medicamentos y plazos con sus padres, o imprima una hoja limpia para su llamada.
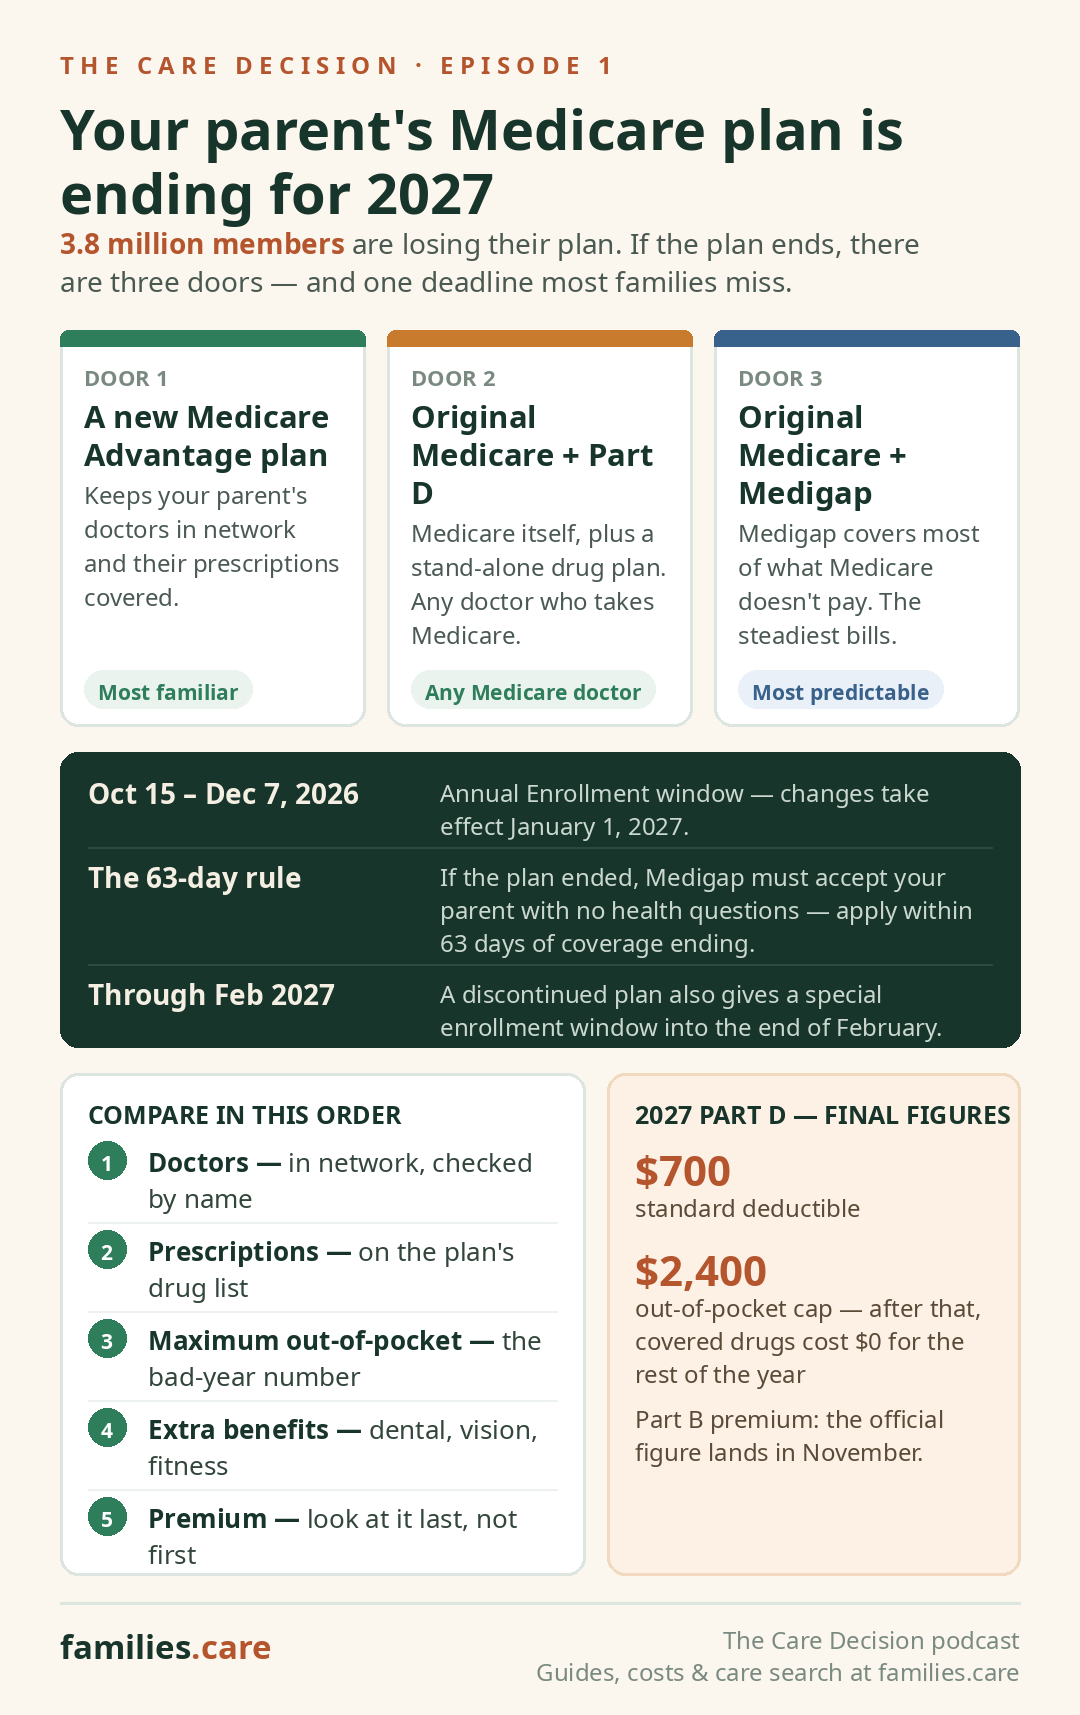
Tarjetas de referencia imprimibles del Episodio 1
Diseñadas para llamadas con aseguradoras, recorridos por residencias y reuniones familiares. Las láminas visuales están en inglés con cifras oficiales verificadas.
Notas del episodio
Roughly 3.8 million people on Medicare are losing their current health plan for 2027 — insurers are leaving counties, ending contracts, or not renewing plans. If your parent got a thick letter from their insurance company in September and set it aside, that letter may be telling them their coverage ends December 31.
In this episode, Maya and Daniel walk through exactly what to do:
- How to tell if your parent is affected — find the Annual Notice of Change, or call the number on the back of the insurance card and ask one question.
- The three doors — another Medicare Advantage plan; Original Medicare with a stand-alone Part D drug plan; or Original Medicare plus a Medigap supplement.
- The most valuable detail in the episode — when a Medicare Advantage plan ends through no fault of the member, they usually get guaranteed-issue rights to buy certain Medigap policies with no medical underwriting — but in most cases only if they apply within 63 days of the old coverage ending.
- How to compare plans in the right order — doctors in network, prescriptions covered, maximum out-of-pocket, extra benefits — premium last.
- The 2027 figures that are final, and the one that isn't — Part D standard deductible $700 and out-of-pocket cap $2,400 are official; the standard Part B premium is still a projection until CMS announces it in November.
- A five-step checklist to work through before December 7 — and why, for discontinued plans, a special enrollment period through the end of February means December 7 is a deadline worth beating, not a cliff edge.
Guides, costs & care search at families.care.
Enlaces mencionados en este episodio
Transcripción completa (guion original en inglés)
Guion íntegro de producción reproducido textualmente tal como fue grabado en inglés.
📖 Leer diálogo completo de Maya y Daniel (23 intervenciones) Expandir ↓
Maya: A quick note before we begin. This episode uses A I generated voices. The script was researched, written, and fact checked by the families dot care team, and the figures in it come from official sources.
Maya: Welcome to The Care Decision, the families dot care podcast, where we take one real decision that families face with an aging parent, and we answer it all the way through. I am Maya.
Daniel: And I am Daniel. Maya, today the decision is a big one, and it is landing in mailboxes all over the country right now.
Maya: It is. Here is the situation. Roughly three point eight million people on Medicare are losing their current health plan for twenty twenty-seven. Their insurers are leaving counties, ending contracts, or simply not renewing the plans. So if your mom or dad got a thick letter from their insurance company in September, the one most people set aside, that letter may be telling them their coverage ends on December thirty-first.
Daniel: Let me ask the question every family asks first. How do you know if your parent is one of the three point eight million?
Maya: You look for one specific document. It is called the Annual Notice of Change, and plans were required to send it in the fall. If the plan is ending entirely, the letter says so plainly, usually in the first page or two. If you cannot find the letter, that is fine. Log into your parent's account on their insurer's website, or call the number on the back of their insurance card, and ask one question: will this exact plan exist in my parent's county in twenty twenty-seven?
Daniel: And the timing matters here, because Medicare's annual enrollment window opens tomorrow, October fifteenth, and it runs through December seventh. Any change your parent makes in that window takes effect on January first, twenty twenty-seven.
Maya: That is the main window, and for most families it is the one to use. But here is the part that calms people down. If your parent's plan is being discontinued, they also get a special enrollment period that runs through the end of February. So December seventh is not a cliff edge for them. It is a deadline worth beating, because coverage choices are widest early, but it is not the last day to act.
Daniel: Okay, so the plan is ending. What are the actual choices?
Maya: There are really three doors. Door one is another Medicare Advantage plan, ideally one that keeps your parent's doctors in network and their prescriptions covered. Door two is going back to Original Medicare, usually paired with a stand-alone Part D drug plan. And door three is Original Medicare plus a Medigap supplement policy, which is the combination that gives the most predictable costs, because Medigap picks up most of what Medicare does not pay.
Daniel: Door three is normally the hard one, because Medigap usually involves health underwriting. The insurer can ask medical questions and can say no.
Maya: Normally, yes. But this is the single most valuable detail in today's episode. When a Medicare Advantage plan ends through no fault of the member, that person usually gets what is called guaranteed issue rights. That means they can buy certain Medigap policies without medical underwriting, with no health questions deciding the answer. There is a clock on it, though. In most cases you apply within sixty-three days of the old coverage ending. Miss that window, and the underwriting questions come back.
Daniel: So the sequence matters. You do not just pick the cheapest premium and move on.
Maya: Exactly. And that brings us to the mistake we see families make every year. They compare premiums. Just premiums. But the number that actually hurts families is the maximum out of pocket, the most the plan can make you pay in a bad year. Two plans can both cost zero dollars a month in premium, and one can cap your yearly exposure thousands of dollars lower than the other.
Daniel: What else belongs on the comparison list?
Maya: Four things, in this order. First, are your parent's actual doctors and hospital in the network, checked by name, not by a brochure. Second, are their exact prescriptions on the plan's drug list, at a tier they can afford. Third, that maximum out-of-pocket number. And fourth, the extra benefits they quietly rely on, like dental, vision, or a fitness benefit, because those often vanish in the new plan and families only notice in March.
Daniel: Let me ground this in the money for twenty twenty-seven, because some of those numbers are now official. What do we know for sure?
Maya: For the Part D drug benefit, the twenty twenty-seven figures are final. The standard deductible is seven hundred dollars, and the out-of-pocket cap, the most anyone pays for covered prescriptions in a year, is two thousand four hundred dollars. Once your parent spends past that cap, their covered drugs cost them nothing more for the rest of the year. What is not final yet is the standard Part B premium. The official announcement comes in November, so treat any number you see for it today as a projection, including ours.
Daniel: And one more piece of good news on the income side. The Social Security cost-of-living adjustment for twenty twenty-seven was announced this morning at three point six percent, which works out to roughly seventy-five dollars a month on the average benefit. That raise helps, but it also means families should do this math after the November premium announcement, not before, because the premium is deducted straight from the Social Security check.
Maya: Which is a perfect summary of the season we are in. So let me give you the checklist we would hand our own families. Step one, find the letter, or call the insurer and confirm whether the plan exists next year. Step two, write down your parent's doctors and their full prescription list, because every comparison runs on those two lists. Step three, compare plans on medicare dot gov with those lists in hand, and check the maximum out of pocket before you look at premiums. Step four, if Medigap might be the right door, protect the guaranteed issue window, and do not let those sixty-three days drift. And step five, make the change before December seventh if you can, so January starts clean.
Daniel: And if a family is walking through this while also comparing care facilities, or trying to work out what care itself will cost next year, that is the other half of what we do. The written version of today's checklist, and our guide to funding care, are both up at families dot care.
Maya: That is our first episode. The Care Decision is about one decision, answered properly, every time. Next time, we take on the question underneath almost every other one: what does memory care actually cost, and what exactly moves that price up or down? I am Maya.
Daniel: And I am Daniel. Thanks for listening, and check on that letter.
Todos los episodios en audio de la serie
Cada episodio responde una decisión concreta sobre cuidado y cobertura en menos de 20 minutos, con el mismo formato limpio y herramientas interactivas.
-
EPISODIO 01 ⏱ 6:18 · Financiamiento
El plan de Medicare de sus padres termina. ¿Qué hacer ahora?
Cerca de 3.8 millones de beneficiarios de Medicare perderán su plan actual para 2027 porque las aseguradoras salen de ciertos condados o no renuevan contratos.
🎧 Escuchando ahora · Episodio 1 -
EPISODIO 02 ⏱ 19:21 · Tipos de cuidado
¿Cuánto cuesta realmente el cuidado de la memoria?
No existe una tarifa nacional oficial para cuidado de la memoria: las familias pagan una tarifa base local (mediana nacional de $6,200/mes en vida asistida según CareScout 2025), más un recargo de 20%–30% por unidad segura de memoria, más los cargos por nivel de cuidado, manejo de medicamentos e incontinencia.
-
EPISODIO 03 ⏱ 10:09 · Financiamiento
Cómo cubren las familias la brecha mensual en vida asistida: las seis puertas
Divide la factura mensual de vida asistida o memoria en tres rubros (Alojamiento, Cuidado Personal y Atención Clínica) para acceder a las Seis Puertas de Financiamiento: Seguro Social, Seguro de Cuidado a Largo Plazo, VA Aid & Attendance (hasta $2,874/mes en efectivo libre de impuestos), exenciones HCBS de Medicaid, patrimonio de la vivienda y deducción médica según el Art.
-
EPISODIO 04 ⏱ 10:19 · Hospital y rehabilitación
El alta hospitalaria en 48 horas y evaluación de centros SNF con CMS 5 Estrellas
Cuando el planificador de alta hospitalaria entrega una lista de cinco centros de enfermería (SNF) con 48 horas para elegir, tres trampas pueden costar miles de dólares.
-
EPISODIO 05 ⏱ 7:49 · Tipos de cuidado
Stay Home or Move? The Home Care vs. Assisted Living Decision
Episode Five answers the question that comes before every other episode in this series: not what a care setting costs, and not how to pay for it, but which setting — care brought into your parent's home, or a move to assisted living.
-
EPISODIO 06 ⏱ 6:48 · Tipos de cuidado
¿Cuidar en casa o buscar una residencia? La decisión en familia
En este primer episodio en español de La Decisión del Cuidado, Maya y Daniel responden la decisión que enfrentan las familias en toda América Latina: seguir cuidando en casa, entre la familia y ayuda contratada, o buscar una residencia privada para adultos mayores.
-
EPISODIO 07 ⏱ 7:12 · Tipos de cuidado
Choosing a Care Home in England: Check the Rating, Then Check Who Pays
This episode answers the care home decision for England in the order that protects families: assessment first, rating second, funding third, contract last.
-
EPISODIO 08 ⏱ 6:19 · Tipos de cuidado
Home or Residential Care? Australia's New Aged Care System Starts With One Assessment
This episode answers Australia's version of the care decision — stay home with Support at Home, or move into residential aged care — inside the system that replaced the old one.
-
EPISODIO 09 ⏱ 6:24 · Tipos de cuidado
Retirement Home or Long-Term Care Home? Ontario's Two Doors
This episode answers the Canadian version of the care decision using Ontario as the worked example — and says plainly that health care is provincial, so other provinces run the same two-door shape with different names, rates and queues.
¿Le resultó útil este episodio para la decisión de su familia?
Valoración anónima de 1 a 5 estrellas · Ayuda a otras familias a priorizar las mejores guías.
Convierta este episodio en un plan local
Los promedios nacionales solo cuentan la mitad. Consulte las tarifas reales, exenciones estatales de Medicaid y residencias verificadas en el estado y ciudad de sus padres.
Calculadora de costos
Comparar costos por estado y ciudad
Consulte medianas CareScout 2025 de vida asistida y estimaciones de cuidado de la memoria.
Directorio verificado
Buscar residencias y agencias locales
Filtre vida asistida, cuidado de la memoria y enfermería especializada por código postal.
Guías estatales y federales
Listas de Medicare, Medicaid y cuidado
Guías paso a paso basadas en reglas oficiales de CMS y programas estatales.